SIP with Insurance in India: Combining Investment and Protection
 Oct, 31 2026
You’re standing at a crossroads. On one side, you want your money to grow so you can retire comfortably or buy that house. On the other, you know that if something happens to you tomorrow, your family needs cash, not a stock portfolio they have to sell during a market crash. For years, Indian financial advisors told us to keep these separate: buy pure term insurance for protection, and invest in mutual funds for growth. But then came the Unit Linked Insurance Plan (ULIP), which promises to do both in one neat package.
Does it actually work? Or is it just a fancy wrapper around expensive fees? This article breaks down how SIPs with insurance work in India, specifically looking at ULIPs and hybrid plans, so you can decide if this combo fits your life or if you should stick to the old-school method.
The Core Problem: Why Mix Money and Safety?
Think about why we buy insurance. It’s not an investment; it’s a safety net. You pay a premium, and if you die, your family gets a payout. That’s it. Now think about investments like stocks or mutual funds. They are risky. They go up, they go down. If you need money urgently, you might lose value.
The appeal of combining them is convenience. Instead of managing two bills-one for a term policy and one for a SIP-you pay one premium. Some people also believe that because part of their money is locked in insurance, they won’t panic-sell their investments when the market drops. Is this psychological lock-in worth the cost? That’s the real question.
How SIP with Insurance Actually Works
In India, the primary vehicle for this combination is the ULIP. Unlike traditional endowment policies where returns are low and fixed, a ULIP lets you choose where your money goes. You can allocate portions to equity funds, debt funds, or balanced funds, similar to mutual funds.
Here is the mechanism:
- Premium Allocation: When you pay your monthly or annual premium, the insurance company deducts charges first. The remaining amount buys units in the funds you selected.
- Death Benefit: Regardless of how the market performs, your nominee receives the higher of the fund value or the sum assured. This guarantees a minimum payout.
- Loyalty Bonuses: Many insurers offer extra units after holding the plan for 5 or 10 years, trying to incentivize long-term retention.
It sounds great on paper. You get market-linked returns plus guaranteed death cover. But the devil is in the details-specifically, the costs.
The Cost Reality: Fees vs. Returns
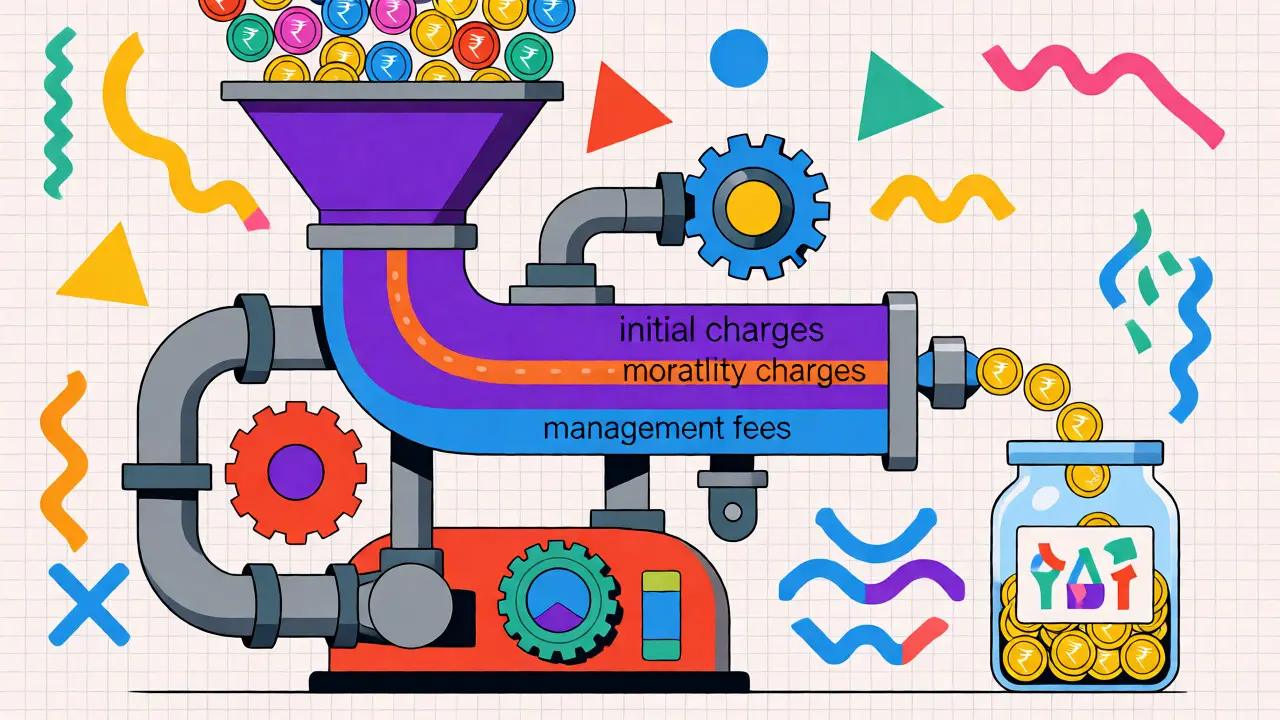
This is where most people get burned. In a regular mutual fund SIP, you might pay an expense ratio of 0.5% to 1.5%. In a ULIP, the charges are layered and often hidden from casual view.
| Feature | ULIP (SIP with Insurance) | Term Insurance + Mutual Fund SIP |
|---|---|---|
| Initial Charges | High (often 20-30% of year 1 premium) | None (for MF); Low admin fee (for Term) |
| Mortality Charge | Deducted monthly based on age/risk | Bundled into Term Premium |
| Fund Management Fee | Up to 1.35% annually | Direct Plans: ~0.1%; Regular: ~0.8% |
| Surrender Penalty | Yes, if exited before 5 years | No penalty for exiting MF SIP |
| Flexibility | Switch between funds allowed (limited free switches) | Full freedom to stop/start anytime |
Notice the "Initial Charges." If you put ₹10,000 into a ULIP in the first month, the insurer might take ₹2,000-₹3,000 immediately to cover sales commissions and setup costs. Your investment starts deep in the red. A mutual fund SIP starts investing almost every rupee from day one.
When Does This Combo Make Sense?
Despite the high fees, there are specific scenarios where a SIP with insurance is the right move.
1. You Lack Discipline: Be honest with yourself. Do you skip SIPs when markets fall? If having your investment tied to a mandatory insurance payment forces you to stay invested, the behavioral benefit might outweigh the fee drag.
2. High Sum Assured Needed Cheaply: Sometimes, buying a huge term cover (e.g., ₹2 Crore) requires medical tests and high premiums if you have health issues. Some ULIPs offer simplified underwriting or guaranteed acceptance for certain amounts, making them accessible when term insurance is denied or too expensive.
3. Tax Optimization Strategy: Both term insurance and ULIPs qualify for tax deductions under Section 80C (up to ₹1.5 Lakh). However, ULIP maturity proceeds are generally tax-free under Section 10(10D) if the premium-to-sum-assured ratio is met. For very high earners who max out other exemptions, this tax efficiency can sometimes offset the higher costs, though recent budget changes have tightened rules on premium limits for tax benefits.
The Better Alternative: Buy Term, Invest Rest
For most Indians, the "Buy Term and Invest the Rest" strategy remains superior. Here’s why:
A Term Insurance Plan provides pure protection at a fraction of the cost. For a healthy 30-year-old male, a ₹1 Crore cover might cost ₹10,000-₹15,000 per year. Compare this to a ULIP offering the same cover, which could cost ₹50,000+ per year due to the investment component and charges.
With the savings from the cheaper term plan, you can start a separate Mutual Fund SIP. You gain total control over your asset allocation, can switch funds without penalties, and enjoy lower expense ratios.
Let’s look at a hypothetical scenario over 20 years:
- Option A (ULIP): Pay ₹50,000/year. After charges, effective investment is lower. Assume 8% net return.
- Option B (Term + MF): Pay ₹15,000 for Term. Invest ₹35,000 in Equity Mutual Funds. Assume 12% gross return (typical for long-term equity).
Even if the ULIP gives a decent 8%, the compounding power of the larger, cheaper investment in Option B usually results in a significantly larger corpus by retirement age, while still keeping the family protected.
Red Flags to Watch Out For
If you are considering a plan that mixes investment and insurance, watch out for these traps:
- The "Guaranteed Return" Myth: Many agents claim ULIPs guarantee returns. They don’t. Only the death benefit is guaranteed. Market risk is yours.
- Lock-in Periods: You cannot withdraw money from a ULIP for the first 5 years. If you face a financial emergency, your money is stuck. Mutual funds allow partial withdrawals anytime.
- Complex Switching Rules: While you can switch between equity and debt funds, some plans charge for more than 4-6 switches a year. Check the fine print.
- Over-insurance: Don’t buy a ULIP just because the agent says you need ₹1 Crore cover. Calculate your actual liability (loans, dependents' needs). Buying excess cover means paying higher mortality charges, eating into your investment.
How to Choose the Right Plan
If you’ve decided that the convenience of a combined plan outweighs the cost, here is how to pick a good one:
- Check the NAV History: Look at the Net Asset Value of the underlying funds over the last 5-10 years. Are they consistent? Avoid funds with erratic performance.
- Compare Mortality Rates: Insurers use different tables to calculate the cost of insurance. Lower mortality rates mean more money goes into your investment pot.
- Evaluate Fund Managers: Who manages the equity portion? If it’s the same team managing top-rated mutual funds, that’s a good sign.
- Read the Policy Document: Ignore the brochure. Read the official document. Look for "Premium Allocation Rate"-it should be 100% after the first year or two.
Final Verdict: Should You Do It?
For the average investor in India, separating protection and investment is usually smarter. It offers transparency, flexibility, and better returns. However, if you struggle with saving discipline, or if you have specific health conditions that make term insurance difficult to obtain, a well-chosen ULIP or hybrid plan can serve as a useful tool.
Don’t let the word "insurance" scare you away from investing, but don’t let the promise of "tax benefits" blind you to high fees. Run the numbers. Ask your advisor: "What is my net return after all charges?" If the answer isn't clear, walk away.
Is a SIP with insurance better than a separate term plan and mutual fund?
Generally, no. Separate term insurance and mutual funds typically offer higher coverage for less cost and better investment returns due to lower fees. However, combined plans (like ULIPs) can be beneficial for individuals who lack investment discipline or have difficulty securing standalone term insurance due to health issues.
What are the main charges in a ULIP?
The main charges include initial allocation charges (deducted upfront), mortality charges (cost of life cover), fund management fees, administration charges, and surrender charges if you exit before the lock-in period (usually 5 years).
Can I withdraw my money from a SIP with insurance anytime?
No, most plans like ULIPs have a mandatory lock-in period of 5 years. During this time, you cannot withdraw the fund value without paying a surrender penalty. After 5 years, partial withdrawals are usually allowed.
Are returns in insurance-based SIPs guaranteed?
In Unit Linked Insurance Plans (ULIPs), investment returns are not guaranteed; they depend on market performance. Traditional endowment plans may offer guaranteed returns, but these are often lower than inflation. Always check if the plan is unit-linked or traditional.
How much tax benefit do I get from SIP with insurance?
Premiums paid towards life insurance policies, including ULIPs, are eligible for deduction under Section 80C of the Income Tax Act, up to ₹1.5 Lakh per year. Maturity proceeds may be tax-free under Section 10(10D), subject to premium-to-sum-assured ratio conditions.